Understanding Wedding Insurance in Singapore
For couples planning their wedding in Singapore, securing insurance offers peace of mind against unforeseen events that could disrupt or financially impact their celebration. Wedding insurance typically encompasses two main types of coverage: cancellation or postponement, and liability. Understanding these options is key to selecting the best policy that aligns with the considerable investment many Singaporean weddings represent.
Why Wedding Insurance is a Smart Investment
Weddings in Singapore are often elaborate affairs, with significant deposits paid for venues, caterers, photographers, and entertainment. A sudden illness, extreme weather, or vendor default can lead to substantial financial losses if these deposits are non-refundable. Liability insurance, on the other hand, protects couples from being held financially responsible for accidents or property damage that may occur during the event, a requirement often stipulated by wedding venues. Given the substantial financial commitment, exploring the best wedding insurance options is a prudent step in wedding planning.
Key Types of Wedding Insurance Coverage
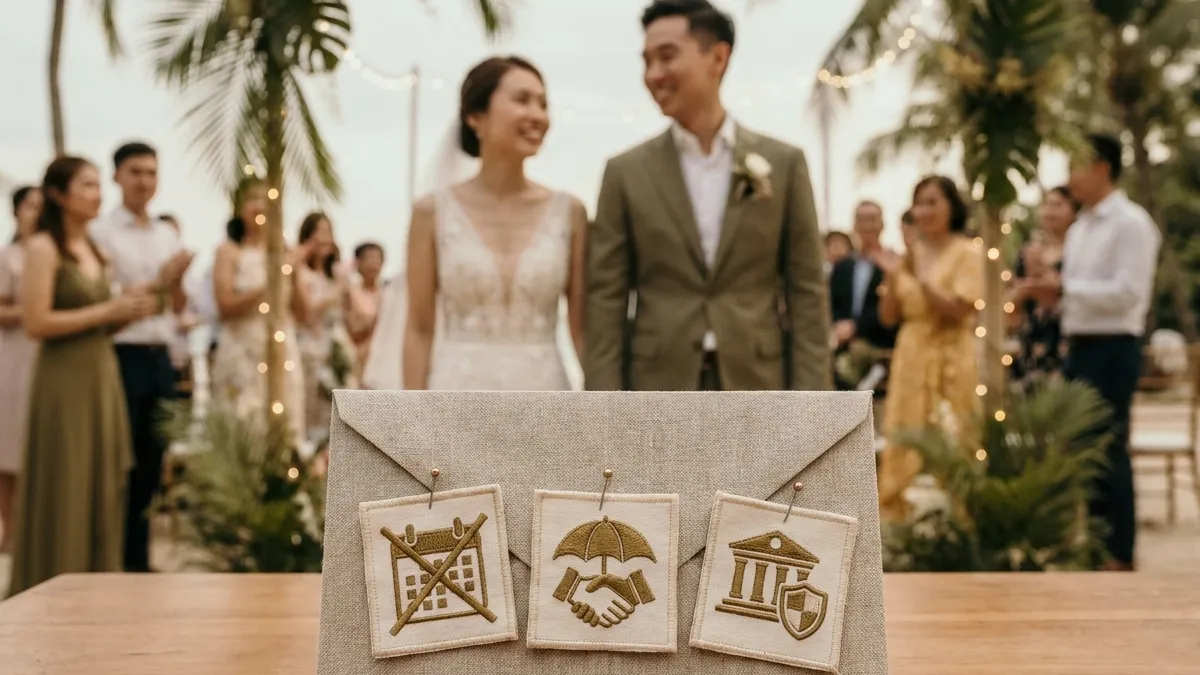
Wedding insurance policies vary, but they generally fall into two primary categories: cancellation/postponement and liability. Many comprehensive policies allow couples to bundle these coverages for enhanced protection.
Wedding Cancellation or Postponement Insurance
This coverage aims to reimburse couples for non-refundable expenses if the wedding must be cancelled, postponed, or interrupted due to circumstances beyond their control. Common covered reasons include:
- Extreme weather conditions that make travel or the venue unsafe.
- Sudden severe illness or injury to the couple or immediate family members.
- Venue issues, such as fire, natural disaster, or the venue becoming unavailable.
- Vendor failure, where a critical vendor (e.g. caterer, photographer) is unable to provide services due to unforeseen circumstances.
It's important to note that policies typically exclude 'change of heart' or pre-existing medical conditions that were known before purchasing the policy. The coverage limit should ideally be set to match the total wedding budget, ensuring all non-refundable deposits are accounted for.
Wedding Liability Insurance
Liability insurance protects couples from financial claims if guests are injured at the wedding or if property damage occurs. This is often a mandatory requirement for booking wedding venues in Singapore. Key aspects include:
- Bodily Injury and Property Damage: Covers medical expenses or repair costs if someone is injured or property is damaged due to the wedding activities.
- Host Liquor Liability: Essential if alcohol will be served. It can protect the couple from liability if an intoxicated guest causes an accident after leaving the event.
- Medical Payments Coverage: May be included to cover minor medical costs for guests injured at the event, regardless of fault.
Liability limits commonly range from S$500,000 to S$5 million. Some policies offer zero deductible, while others may require a deductible for property damage claims. Couples should check with their chosen venues for specific liability coverage requirements, as these can influence the minimum policy limit needed.
Factors Influencing Wedding Insurance Costs in Singapore
The cost of wedding insurance in Singapore is not a fixed figure and depends on several variables. While specific pricing for the Singapore market requires direct quotes from insurers, general factors influencing premiums internationally include:
- Coverage Limits: Higher coverage amounts for cancellation or liability will naturally lead to higher premiums.
- Wedding Budget: A larger overall wedding budget often correlates with a higher cost of insurance, especially for cancellation coverage.
- Guest Count: More guests can increase potential liability risks.
- Services Offered: Including extras like serving alcohol or hiring specific vendors might affect the price.
- Deductible Amount: Policies with lower or zero deductibles typically have higher premiums.
- Time of Year and Location: Weddings during peak seasons or in areas prone to certain natural events might see adjusted rates.
Internationally, cancellation coverage can start around S$125, and liability coverage around S$150 [insure.com]. Couples should obtain multiple quotes to compare offerings and pricing.
Choosing the Right Insurance Policy
Selecting the best wedding insurance options involves a careful review of personal needs and potential risks.
Insider Tip: Venue Requirements are Paramount
Before comparing insurance policies, always verify your venue's specific insurance requirements. Many Singaporean venues mandate a minimum liability coverage amount. Failing to meet this can jeopardise your booking or incur additional venue fees. Having this information upfront will narrow down your search considerably.
Insider Tip: Review Existing Coverage First
Before purchasing a new policy, check if any existing insurance provides partial coverage. For instance, homeowners or renters insurance might cover theft or damage to gifts. If a relative is hosting at their home, their homeowners policy might offer some liability protection, though host liquor liability is often an add-on. Always confirm with your insurer to avoid overlapping coverage or gaps.
What to Look For in a Policy:
- Comprehensive Coverage: Ensure the policy covers your most significant financial exposures, from non-refundable deposits to potential liability claims.
- Reasonable Deductibles: Understand the deductible amounts for different types of claims. A high deductible on cancellation insurance might mean you don't recoup small deposits.
- Clear Exclusions: Read the policy's exclusion list carefully. Common exclusions include acts of war, terrorism, and communicable diseases like COVID-19, although some policies may offer riders for specific events.
- Vendor and Guest Count Flexibility: Ensure the policy can accommodate changes in guest count or specific vendor arrangements if needed.
Wedding Insurance FAQs
Do I need wedding insurance for my Singaporean wedding?
While not always mandatory by law, many wedding venues in Singapore require couples to provide proof of liability insurance. Beyond venue requirements, wedding insurance can protect your significant financial investment against unforeseen cancellations or disruptions.
What specific events does wedding cancellation insurance typically cover in Singapore?
Typical covered events include extreme weather rendering the venue unsafe or inaccessible, sudden serious illness or injury of the couple or immediate family, venue issues like fire or natural disaster, and critical vendor no-shows. It generally does not cover 'change of heart' or known pre-existing conditions. Always check the policy's specific wording.
How much does wedding insurance typically cost in Singapore?
Internationally, basic wedding cancellation coverage can start around S$125, and liability coverage around S$150 [insure.com]. The final cost in Singapore will depend on the selected coverage limits, wedding budget, guest count, and specific policy details. Obtaining quotes from different providers is essential for accurate pricing.
Can wedding insurance cover destination weddings from Singapore?
Some specialised insurers offer policies for destination weddings, such as Markel [cnbc.com]. However, couples should carefully review the policy's terms regarding international coverage, as many standard policies are limited to domestic events.
What is the difference between wedding liability and cancellation insurance?
Wedding liability insurance protects you financially if guests are injured or property is damaged at your event. Cancellation insurance reimburses you for non-refundable expenses if the wedding has to be called off, postponed, or interrupted due to covered reasons.
How much wedding liability insurance do I need?
This is often determined by your venue's requirements, which typically specify a minimum coverage amount, commonly ranging from S$500,000 to several million dollars. It's crucial to check with your venue for their exact stipulations.
Does wedding insurance cover wedding photography and videography packages?
Yes, if the photographer or videographer is a vendor who defaults on their contract or is unable to provide services due to a covered reason, the cancellation or postponement coverage can help recoup any non-refundable deposits paid for their services, such as those from a PGVG package.
Are there wedding insurance providers specifically in Singapore?
While there may not be many insurance providers exclusively for weddings in Singapore, local general insurers and international companies offering event insurance often provide policies that can cover weddings. It is advisable to consult with insurance brokers or directly with insurance companies operating in Singapore.
What is a deductible in wedding insurance?
A deductible is the amount of money you are responsible for paying out-of-pocket before your insurance coverage kicks in. For example, if your policy has a S$500 deductible for property damage and the damage costs S$2,000, you would pay S$500, and the insurance would cover the remaining S$1,500. Some policies may offer no deductible options, especially for liability claims.
Can wedding insurance cover the cost of a wedding planner?
If a wedding planner is a contracted vendor who fails to deliver services due to a covered reason, the cancellation or postponement coverage portion of your wedding insurance policy may help recoup any non-refundable payments made for their services.
How soon before the wedding should I buy wedding insurance?
It is generally recommended to purchase wedding insurance as soon as possible after booking your venue and other key vendors. This ensures that deposits already paid are protected. Many policies have waiting periods or require purchase a certain number of days before the wedding date.